
Mortgage credit score changes moved from talk to action this fall. On October 8, FHA published Mortgagee Letter 2026-11, which sets the rules for using VantageScore 4.0 and FICO 10T alongside Classic FICO on FHA loans with case numbers assigned on or after January 1, 2027. Conventional loans sold to Fannie Mae and Freddie Mac can already use VantageScore 4.0, and since October 1, both companies price those loans the same way, regardless of which of the two models is used for the loan. Here is what that means if you plan to buy a home in Texas.
TL;DR:
- FHA will accept VantageScore 4.0 and FICO 10T, in addition to Classic FICO, for case numbers assigned on or after January 1, 2027, under Mortgagee Letter 2026-11 dated October 8.
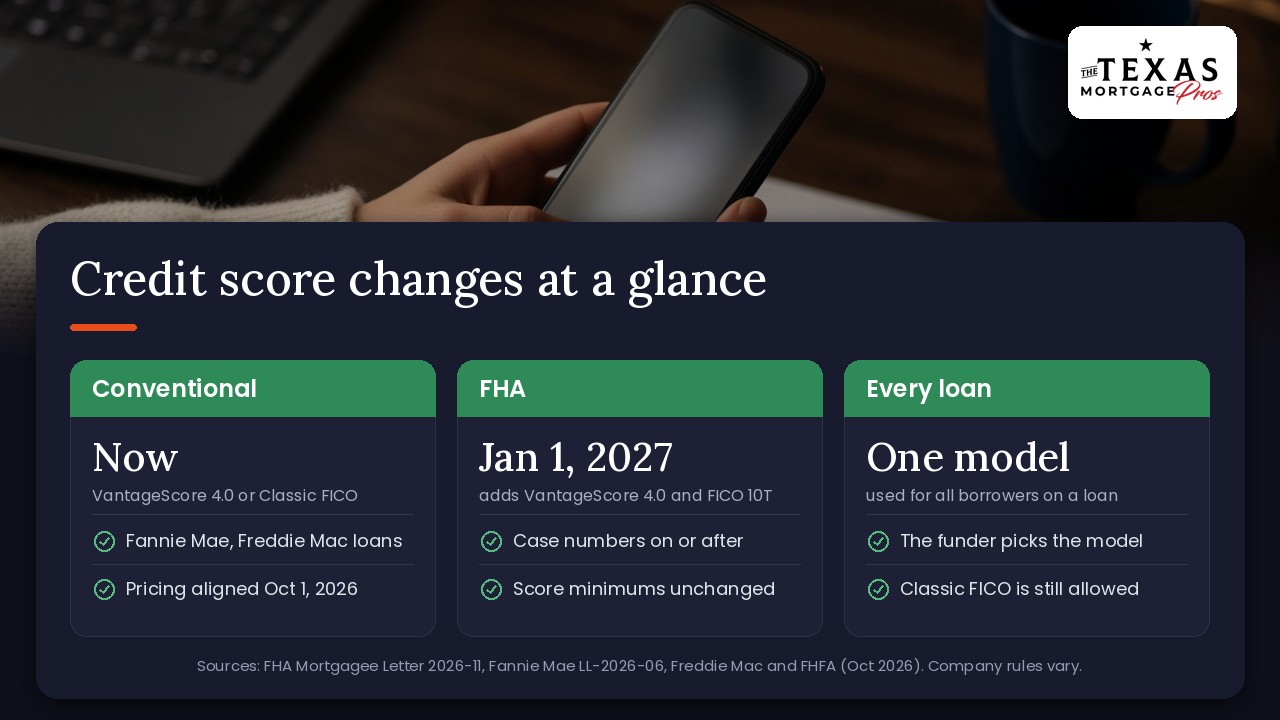
- For conventional loans, every mortgage company approved by Fannie Mae and Freddie Mac has been allowed to use VantageScore 4.0 since September 9, and pricing has been aligned across Classic FICO and VantageScore 4.0 since October 1.
- The company that funds your loan chooses the score model, and the same model must be used for every borrower on the loan. The score in your credit app may not be the score used for your mortgage.
- What has not changed: FHA still requires a tri-merge credit report, and its minimum credit score thresholds stay the same. A newer model does not guarantee approval or better pricing.
- The best preparation is still the basics: check your credit reports, dispute errors, pay on time, keep balances low and avoid new credit while you shop.
Table of Contents
- What Changed in Mortgage Credit Scoring This Fall?
- Why Does Your Credit Score Matter More Right Now?
- What Is VantageScore 4.0, and How Is It Different?
- What Has Not Changed?
- FHA vs. Conventional: When Do the New Scores Apply?
- Will a Different Score Model Help You?
- Credit Checklist Before You Get Pre-Approved
- Get a Personalized Review
- Sources
What Changed in Mortgage Credit Scoring This Fall?
For decades, loans sold to Fannie Mae and Freddie Mac required credit scores from a single model, Classic FICO, according to the Federal Housing Finance Agency (FHFA). That started to change with a limited rollout in April 2026. Three updates in the last few weeks have made the change real for buyers:
- September 9, conventional loans: Fannie Mae and Freddie Mac opened VantageScore 4.0 to all of their approved mortgage companies without prior written approval, FHFA said. Those companies can still use Classic FICO instead.
- September 30, conventional pricing: Fannie Mae’s Lender Letter LL-2026-06 aligned its loan-level price adjustments across Classic FICO and VantageScore 4.0 and removed the separate VantageScore pricing grids, effective for loans purchased or delivered on or after October 1. Freddie Mac aligned its credit fees across the two models the same day. In plain terms, the same pricing grid now applies whichever of the two models is used for the loan.
- October 8, FHA loans: HUD’s Mortgagee Letter 2026-11 updated how FHA picks the credit score that counts when more than one scoring model is on a credit report. It takes effect for FHA case numbers assigned on or after January 1, 2027. FHA announced that date on September 10 along with a Preparedness Guide for FHA-approved mortgage companies.
Industry coverage frames this as a phased change, not a switch flipped overnight. “This is a phased expansion of credit scoring options. Eligibility, timing, and operational requirements remain program-specific.”
Why Does Your Credit Score Matter More Right Now?
Credit scores help decide whether you are offered a mortgage and the interest rate you receive, the Consumer Financial Protection Bureau (CFPB) explains. That matters more when borrowing costs are high. The Mortgage Bankers Association said mortgage rates moved to their highest level in almost three years in the week ending October 2, and purchase applications were 15% lower than a year earlier.
Texas buyers are feeling it. Texas REALTORS® said many agents described buyers who were surprised by how much property taxes, homeowners insurance, and mortgage interest rates affected what they could comfortably afford. When the budget is tight, it pays to know exactly how your credit will be read before you apply.
What Is VantageScore 4.0, and How Is It Different?
VantageScore 4.0 and FICO 10T are newer credit score models that FHFA validated for mortgage use in 2022. According to FHFA, additional data sources, including rent payment history, are considered. HUD’s Mortgagee Letter says the new models use trended data, which looks at your credit behavior over time rather than a single snapshot, and can use non-traditional credit data such as rent and utilities.
A few points to keep in mind:
- A model can only score what is in your credit file. If your rent or utility payments are not reported to the credit bureaus, a newer model has nothing extra to work with.
- Trended data looks at your pattern. Because the newer models look at how you have managed credit over time, a consistent track record matters, not just where your balances stand on the day your credit is pulled.
- Your app score may not be your mortgage score. The CFPB notes there are multiple versions of the FICO score, and each weighs the information in your report differently. A free score from a website or card issuer may use a different model or version than the one pulled for your mortgage.
- FICO 10T is approved but not in use yet for Fannie Mae and Freddie Mac. FHFA says FICO 10T is not currently eligible for delivery, and more guidance will be provided when it is. FHA plans to accept it starting January 1, 2027.
What Has Not Changed?
A lot stays the same, and that is just as important for planning:
- Your full credit report still matters. FHA will continue to require a tri-merge credit report, which pulls from all three nationwide credit bureaus, and FHFA says the change does not initially alter Fannie Mae and Freddie Mac credit reporting requirements.
- FHA’s minimum credit score thresholds are unchanged. The Mortgagee Letter says existing thresholds remain the same regardless of which model is used.
- Classic FICO is still allowed. FHFA expects Classic FICO to be retired at a future date, but no date has been announced, and FHFA says it will provide advance notice.
- FHA loans follow today’s rules until January 1, 2027. HUD’s Preparedness Guide tells FHA-approved mortgage companies to keep using the existing credit policy in Handbook 4000.1 until the new guidance takes effect.
- Manually underwritten conventional loans still use Classic FICO. Fannie Mae’s Lender Letter says VantageScore 4.0 applies to loans run through its Desktop Underwriter system.
- Credit is one piece of the file. Income, debts, assets, the property, and program rules still have to fit. A different score model does not change those requirements.
FHA vs. Conventional: When Do the New Scores Apply?
Conventional loans (Fannie Mae and Freddie Mac): VantageScore 4.0 is available now. FHFA says the mortgage company decides which model, Classic FICO or VantageScore 4.0, to use for each loan, and all borrowers on the same loan must be scored with the same model. Fannie Mae requires mortgage companies that choose VantageScore 4.0 to request it from all three credit bureaus.
FHA loans: The new models apply to FHA case numbers assigned on or after January 1, 2027, for FHA’s forward mortgage programs. If your FHA case number is assigned before then, today’s rules apply. Starting in January, the Mortgagee Letter sets these steps:
- For each score model in the report, use the middle score if three different scores are reported, the lower score if there are two, or the only score if there is one.
- Each borrower’s score is the lowest of those model scores.
- The loan score is the lowest among all borrowers.
HUD’s Preparedness Guide adds an important detail: if a mortgage company submits more than one model to FHA’s TOTAL Scorecard, every model must receive an Accept for the loan to be approved. If any one of them gets a Refer, the result is Refer. In other words, more scores do not mean more chances. A mortgage company may remove a model and resubmit, and some may prefer to submit a single model for all borrowers.
These announcements cover conventional loans sold to Fannie Mae and Freddie Mac and FHA-insured loans. If you are considering a VA, USDA, or jumbo loan, ask your mortgage broker which scoring rules apply. Still choosing a loan type? Our comparison of FHA vs. conventional home loans can help.
Will a Different Score Model Help You?
Maybe, maybe not. A VantageScore 4.0 result will not be better on every file, National Mortgage Professional reported on October 1. Classic FICO may still produce better results for some borrowers, while the newer model may make little or no difference for others. The same report said comparing the two may matter most for borrowers near a pricing or eligibility threshold.
Because the company funding each loan chooses the model, options can vary from one mortgage company to the next, and approval of a model does not guarantee availability for every loan program. Questions worth asking your mortgage broker:
- Which score models can be used for the loan type I am considering?
- Will you pull both Classic FICO and VantageScore 4.0, and can we see how each one reads my file?
- If my score is close to a program or pricing cutoff, what would help most before I apply?
- If I apply for an FHA loan now, will my case number be assigned before or after January 1, 2027?
Credit Checklist Before You Get Pre-Approved
No matter which model is used, the habits that help your credit are the same. The CFPB recommends paying all your bills on time, applying only for the credit you need, and not using too much of the credit available to you.
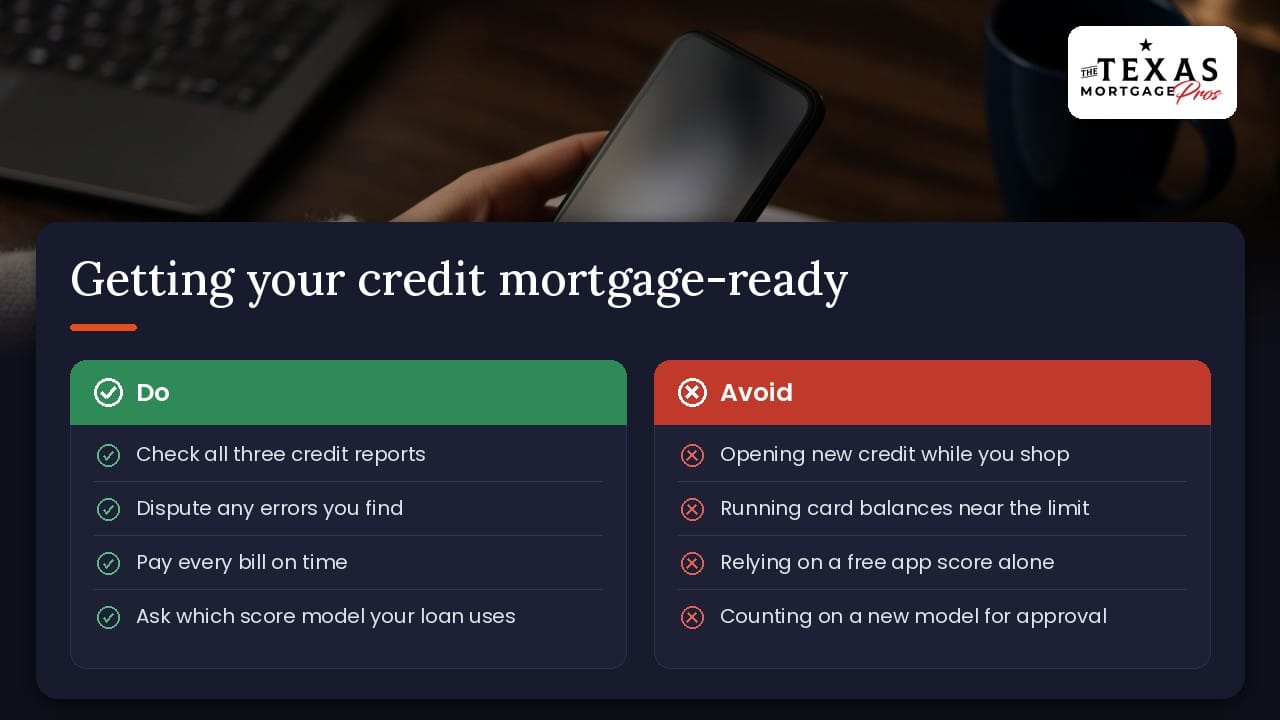
- Pull your free credit reports. You can get free reports from Equifax, Experian, and TransUnion at AnnualCreditReport.com, and you may be able to view them more often online, according to the CFPB. Checking your own credit does not affect your scores.
- Dispute errors early. The CFPB says to dispute errors in writing with the credit reporting company and with the company that supplied the information, and include copies of supporting documents. Furnishers generally must investigate within 30 days, so start well before you apply. If a correction comes through mid-process, ask your mortgage broker about a rapid rescore.
- Keep paying every bill on time. With trended data, a steady record counts.
- Keep card balances well below your limits. Using too much of your available credit can weigh on your scores.
- Hold off on new credit. The CFPB suggests avoiding new credit cards, car loans, or other loans right before or during the mortgage process.
- Shop for your mortgage within a short window. The CFPB says multiple mortgage credit checks within a 45-day window are recorded as a single inquiry.
- Lift any credit freeze before you apply. The nationwide credit reporting companies must freeze and unfreeze your reports for free, the CFPB says. A freeze can keep your report from being pulled for your mortgage application, so plan ahead.
- Get your co-borrower ready, too. The same model is used for everyone on the loan, and FHA uses the lowest borrower score for the loan.
When your credit is in order, our Texas mortgage pre-approval guide walks through the next steps, and our guide to Texas first-time homebuyer programs covers assistance options.
— Gerry Nicodemus
Get a Personalized Review
Every buyer’s credit file is different. If you are weighing an FHA loan or another home loan in Texas and want to know which score models could apply to you and what to work on before you apply, call (281) 801-6965 to talk with a mortgage professional at The Texas Mortgage Pros, a mortgage broker. You can also review our FHA loan requirements to see where you stand today.
Last verified: October 9, 2026. Credit score policies, loan program rules, and underwriting requirements change often. Check each source for the latest details.
This article is general information, not legal, tax, or financial advice. It is not a commitment to lend or an offer of credit. Loan approval and terms are subject to underwriting, program guidelines, and eligibility. No credit score model guarantees approval, a particular score, or particular loan terms, and the score model used for a loan is chosen by the company funding the loan under program rules. Consult a qualified financial professional about your own circumstances before acting on anything here.
The Texas Mortgage Pros is not affiliated with, endorsed by, or sponsored by HUD, FHA, FHFA, Fannie Mae, Freddie Mac, the CFPB, the Mortgage Bankers Association, Texas REALTORS, FICO, VantageScore Solutions, Equifax, Experian, TransUnion, or any other organization named in this article. Third-party names are used only to cite their published information.
Company NMLS #2665861 • NMLS Consumer Access • Equal Housing Opportunity • (281) 801-6965
Sources
- U.S. Department of Housing and Urban Development, Mortgagee Letter 2026-11, Updated Minimum Decision Credit Score Methodology for the Implementation of Alternative Credit Scores (October 8, 2026)
- U.S. Department of Housing and Urban Development, FHA Alternative Credit Scores Preparedness Guide (released September 10, 2026)
- WRE News, FHA Sets Jan. 1 Start for VantageScore 4.0 and FICO 10T (September 11, 2026)
- Federal Housing Finance Agency, Credit Scores (last updated October 2, 2026)
- Fannie Mae, Lender Letter LL-2026-06, VantageScore 4.0 Broad Lender Availability (updated September 30, 2026)
- Freddie Mac, Credit Score Models and Reports Initiative (September 30, 2026 update)
- National Mortgage Professional, UWM Removes 20-Point VantageScore Adjustment (October 1, 2026)
- Asurity, More Choices in Mortgage Credit Scoring: What Lenders Should Know (October 5, 2026)
- Mortgage Bankers Association, Mortgage Applications Decrease in Latest MBA Weekly Survey (October 7, 2026)
- Texas REALTORS (via PR Newswire), Texas Homebuyers Had Less Competition and More Choices This Year, According to a Survey of Realtors (October 6, 2026)
- Consumer Financial Protection Bureau, What Happens When a Mortgage Lender Checks My Credit? (last reviewed August 28, 2026)
- Consumer Financial Protection Bureau, How Do I Get a Free Copy of My Credit Reports?
- Consumer Financial Protection Bureau, How Do I Dispute an Error on My Credit Report? (last reviewed September 2, 2026)
- Consumer Financial Protection Bureau, What Is a FICO Score?
Recommended
- Texas Seller Concessions: How Buyers Can Negotiate as Competition Cools
- Mortgage Pre-Approval in Texas: Your 2026 Buying Guide
- Texas Homeowners Insurance Costs: What Buyers Should Know This Fall
- FHA Loan Requirements

Gerry is a licensed mortgage loan originator and digital marketer with 25+ years in the mortgage business, specializing in conversion rate optimization, SEO, AI Overviews, and generative engine optimization (GEO) for the mortgage and real estate industry. Today he builds agentic intelligent systems, meaning AI agents that research, create content, nurture leads, and handle follow-up, to help mortgage and real estate business owners get found online, convert more leads, and scale. Gerry pairs decades of hands-on industry knowledge with the latest AI tools, so his clients stay a step ahead of the market.