
With fewer buyers competing for the same homes, Texas seller concessions are worth putting back into your offer strategy this fall. In the 2026 Texas Homebuying Experience Report released October 6, 69% of Texas REALTORS® surveyed said their buyer clients did not compete against other offers, up from 57% last year. Less competition can give you room to ask the seller to help with closing costs, rather than only negotiating on price.
TL;DR:
- Texas REALTORS® says buyers had less competition and more time to shop in 2026. Nearly a third of agents said their most recent buyer bought after making only one offer.
- Houston pending sales were down 23.7% from a year earlier in the week ended September 28, and Texas new-home inventory was up 2.2% from a year earlier in August.
- Mortgage rates hit their highest level in almost three years in late September, according to the Mortgage Bankers Association, which makes the cash you need at closing even more important to plan.
- A seller concession (often called a seller credit) is money the seller agrees to put toward your closing costs. Each loan type has its own limit, and a credit generally cannot pay your down payment.
- Get a closing cost estimate before you write the offer, put the credit in the contract, and check that it shows up on your Loan Estimate and Closing Disclosure.
Table of Contents
- Why Do Texas Buyers Have More Negotiating Room This Fall?
- Why Does Cash to Close Matter More Right Now?
- What Are Seller Concessions?
- How Much Can a Seller Contribute by Loan Type?
- Price Cut or Seller Credit: Which Should You Ask For?
- How Do You Ask for Seller Concessions in Texas?
- Seller Concession Checklist Before You Make an Offer
- Get a Personalized Review
- Sources
Why Do Texas Buyers Have More Negotiating Room This Fall?
The new Texas REALTORS® report covers members’ experiences with buyer clients from January through August 2026. Besides the drop in competing offers, 71% of agents said their buyers felt they had plenty of time or a reasonable amount of time to search, and only 2% said buyers felt very pressed for time. Nearly a third said their most recent client who bought a home did so after making only one offer.
“Buyers are benefiting from more choices and more time to make decisions, but many are facing affordability challenges,” said Texas REALTORS® Chairman Jennifer Wauhob. The report reflects agent perceptions rather than every Texas sale, as WRE News noted in its October 7 coverage, but recent market data points the same way:
- Houston: In the Houston Association of REALTORS® weekly snapshot for the week ended September 28, pending sales fell 23.7% and closings fell 21% from the same week a year earlier, while new listings were up 0.5%, Houston Agent Magazine reported on October 2. The week before, pending sales were down 26.8%, according to its September 25 report.
- New homes statewide: The HomesUSA.com Texas New Home Sales Report released September 21 showed 37,031 active new-home listings in Dallas-Fort Worth, Houston, Austin and San Antonio in August, up 2.2% from a year earlier, while pending sales were down 10.7%. CEO Ben Caballero said builders “must work harder for each sale.”
That does not mean every seller will say yes. The same HomesUSA.com report found new homes still sold for close to asking price on average, and weekly numbers can swing. Conditions vary by city, neighborhood, and price range, so ask your real estate agent what nearby homes have sold for and whether sellers in that area have been paying toward buyers’ costs.
Why Does Cash to Close Matter More Right Now?
Borrowing costs climbed quickly at the end of September. In its October 7 weekly survey, the Mortgage Bankers Association said mortgage rates moved to their highest level in almost three years in the week ending October 2. Purchase applications were 15% lower than the same week a year earlier, and FHA purchase applications fell 6% in a single week. MBA Deputy Chief Economist Joel Kan said: “the jump in borrowing costs has caused many potential borrowers to step back from the purchase market.”
Texas REALTORS® heard something similar from buyers. In open-ended comments, agents described clients who were surprised by how much property taxes, homeowners insurance and mortgage interest rates affected what they could comfortably afford. (Our guide to Texas homeowners insurance costs covers the insurance side.) When the monthly budget is tight, the cash you need at closing can be the next hurdle. That is where a seller concession can help.
What Are Seller Concessions?
A seller concession, often called a seller credit or seller contribution, is an amount the seller agrees to pay toward the buyer’s costs of buying the home. Lenders and loan programs call it an “interested party contribution,” because the money comes from someone who benefits from the sale, such as the seller, builder, or a real estate agent.
Depending on the loan program, a seller credit can typically go toward:
- Lender and third-party closing costs, such as origination, appraisal, and title charges
- Prepaid items, such as the first year of homeowners insurance and the initial deposit into your escrow account
- Discount points or an interest rate buydown, within the program’s limits
The Consumer Financial Protection Bureau explains that the Estimated Cash to Close on your Loan Estimate subtracts any amount the seller has agreed to pay toward your closing costs. Before closing, the CFPB recommends checking that the seller credit on your Closing Disclosure matches what you agreed to with the seller.
How Much Can a Seller Contribute by Loan Type?
Every major loan type caps how much the seller and other interested parties can contribute. These are the published program limits. Your lender may apply stricter rules, and the credit can never exceed your actual eligible costs.
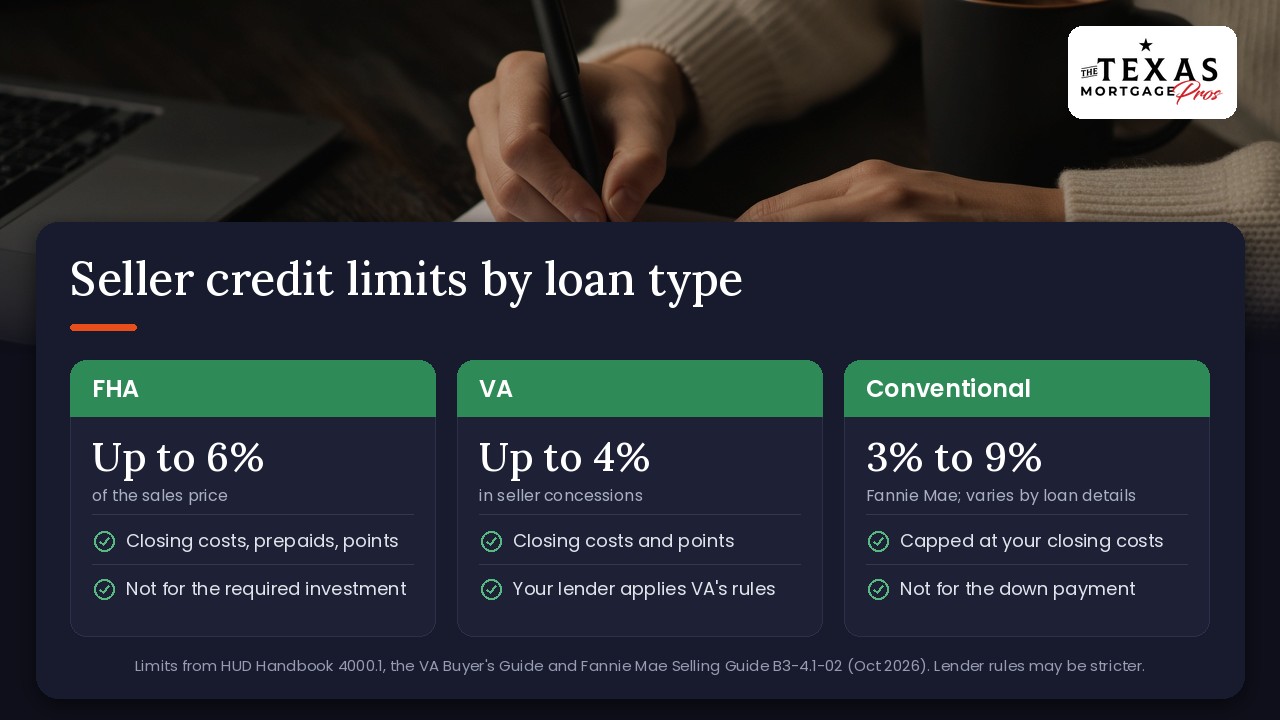
- FHA loans: HUD’s Single Family Housing Policy Handbook 4000.1 lets interested parties contribute up to 6% of the sales price toward the borrower’s origination fees, other closing costs, prepaid items, and discount points. The 6% includes seller-paid interest rate buydowns. Contributions above 6% or above your actual costs are treated as an inducement to purchase and cannot be used toward the borrower’s minimum required investment. Real estate commissions the seller customarily pays do not count toward the limit.
- VA loans: The VA’s Home Loan Guaranty Buyer’s Guide says sellers can pay closing costs and discount points, and that concessions can be up to 4%. The guide describes the 4% as a share of the sale in one place and of the loan amount in another, and points to Chapter 8 of the VA Lenders Handbook for the full rules, so ask your lender how it applies to your purchase.
- Conventional loans: Fannie Mae’s Selling Guide caps financing concessions at 3%, 6% or 9% of the lower of the sales price or appraised value for a primary residence or second home, depending on the loan-to-value ratio, and at 2% for an investment property. The concessions cannot exceed your closing costs and cannot be used for the down payment or required reserves. Loans sold to Freddie Mac follow Freddie Mac’s own guidelines.
Going over a limit has consequences. Under Fannie Mae’s rules, for example, contributions above the cap are treated as sales concessions and are subtracted from the sales price, which can change the loan amount you qualify for. That is why your lender should review the contract terms before you sign. If you are still choosing a loan type, our comparison of FHA vs. conventional home loans can help.
Price Cut or Seller Credit: Which Should You Ask For?
A seller may be willing to give up a similar amount either way, but the two work differently for you:
- A lower price reduces the amount you borrow over the life of the loan and can lower costs that are based on the price.
- A seller credit lowers the cash you need at closing, which can matter more if your savings are limited.
- A seller-paid buydown uses the credit to pay discount points or a temporary buydown. It counts toward the program limit, and whether it makes sense depends on how long you expect to keep the loan.
There is no single right answer. Ask your lender to show each option on a Loan Estimate or written fee worksheet so you can compare your cash to close and your costs over the years you plan to own the home. If a builder offers incentives tied to its preferred lender, the CFPB recommends requesting Loan Estimates from more than one lender so you can compare the full offer.
How Do You Ask for Seller Concessions in Texas?
- Talk with a lender before you shop. Find out which loan type fits you, what your estimated closing costs are, and how much seller help that loan allows.
- Let your agent read the market. Recent sales, days on market, and price reductions on similar homes show how much room a seller may have.
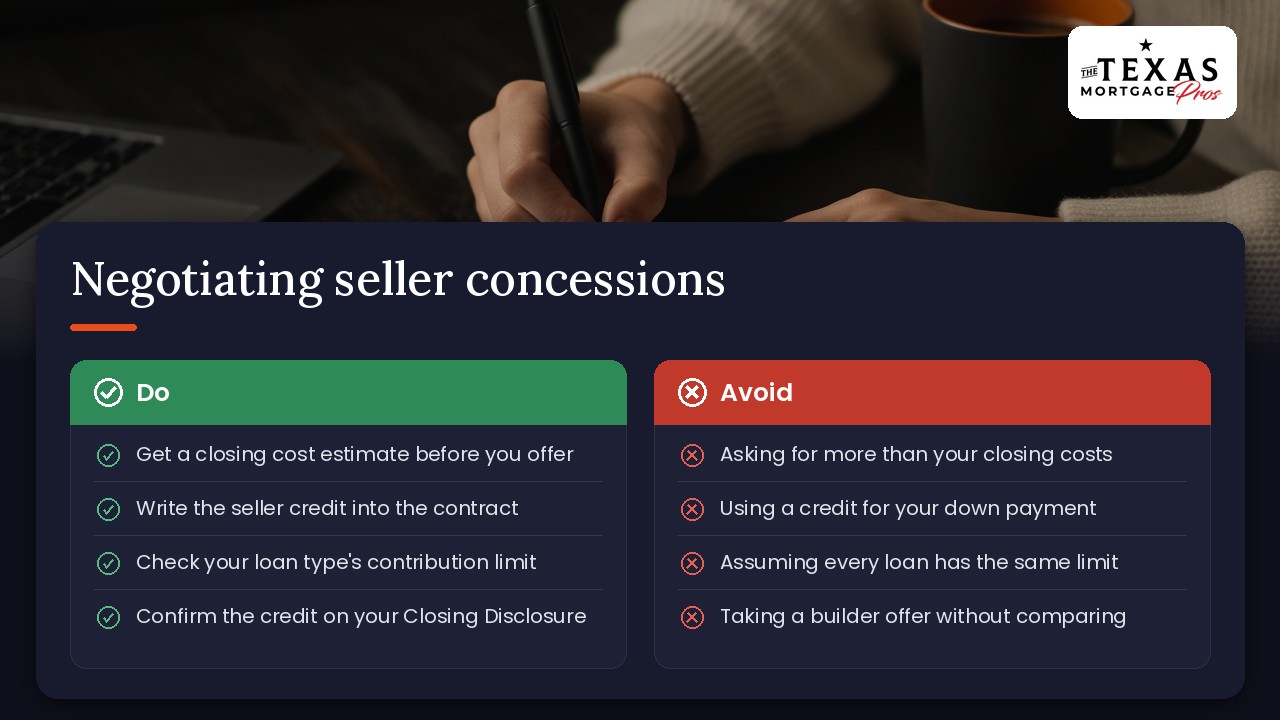
- Write a specific dollar amount into the contract. Your agent will put the seller’s contribution toward your expenses in the purchase contract. A vague promise is hard to enforce.
- Keep the request within your costs and your limit. Asking for more than you can use does not help you and can complicate underwriting and the appraisal review.
- Check your closing documents. Confirm the credit on your updated Loan Estimate and on the Closing Disclosure you receive before closing.
Seller Concession Checklist Before You Make an Offer
- Get an estimate of your closing costs and prepaids from your lender for the price range you are shopping.
- Confirm your loan type’s contribution limit and any stricter lender rules.
- Decide what to ask for: a lower price, a closing cost credit, a buydown, or a mix.
- Ask your agent about local norms and how long similar homes have been on the market.
- Compare builder incentives with Loan Estimates from more than one lender.
- Review the Closing Disclosure to make sure the seller credit matches your contract.
Combining a seller credit with assistance can stretch your cash further. See our guides to Texas first-time homebuyer programs and the Texas Mortgage Credit Certificate.
— Gerry Nicodemus
Get a Personalized Review
Every buyer’s situation is different. If you are weighing an FHA loan or another home loan in Texas and want to know how much seller help your loan allows and how a credit would change your cash to close, call (281) 801-6965 to talk with a mortgage professional. You can also review our FHA loan requirements to see where you stand today.
Last verified: October 8, 2026. Loan program rules, lender requirements, and market data change often. Check each source for the latest details.
This article is general information, not legal, tax, or financial advice. It is not a commitment to lend or an offer of credit. Loan approval and terms are subject to underwriting, program guidelines, and eligibility. Seller concessions are negotiated between buyer and seller, and a seller is not required to offer them. Consult your real estate agent and a qualified financial professional about your own circumstances before acting on anything here.
The Texas Mortgage Pros is not affiliated with, endorsed by, or sponsored by HUD, FHA, the Department of Veterans Affairs, Fannie Mae, Freddie Mac, the CFPB, the Mortgage Bankers Association, Texas REALTORS, the Houston Association of REALTORS, HomesUSA.com, or any other organization named in this article. Third-party names are used only to cite their published information.
Company NMLS #2665861 • NMLS Consumer Access • Equal Housing Opportunity • (281) 801-6965
Sources
- Texas REALTORS (via PR Newswire), Texas Homebuyers Had Less Competition and More Choices This Year, According to a Survey of Realtors (October 6, 2026)
- WRE News, Texas Buyers Face Less Competition, but Taxes, Insurance and Rates Keep Affordability Tight (October 7, 2026)
- Mortgage Bankers Association, Mortgage Applications Decrease in Latest MBA Weekly Survey (October 7, 2026)
- Houston Agent Magazine, Pending, Closed Listings Decline Again in Houston (October 2, 2026)
- Houston Agent Magazine, Houston Sales Activity Continues to Trend Below Year-Ago Levels (September 25, 2026)
- HomesUSA.com (via GlobeNewswire), Texas New Homes Spend Fewer Days on Market for Fourth Straight Month Yet Sales Decline (September 21, 2026)
- U.S. Department of Housing and Urban Development, Single Family Housing Policy Handbook 4000.1
- U.S. Department of Veterans Affairs, VA Home Loan Guaranty Buyer’s Guide
- Fannie Mae Selling Guide, B3-4.1-02, Interested Party Contributions (IPCs)
- Consumer Financial Protection Bureau, Loan Estimate Explainer
- Consumer Financial Protection Bureau, Closing Disclosure Explainer
Recommended
- Texas Homeowners Insurance Costs: What Buyers Should Know This Fall
- Texas Mortgage Credit Certificate: A Fall Tool as Buyers Gain Leverage
- Texas First-Time Homebuyer Programs
- FHA Loan Requirements

Gerry is a licensed mortgage loan originator and digital marketer with 25+ years in the mortgage business, specializing in conversion rate optimization, SEO, AI Overviews, and generative engine optimization (GEO) for the mortgage and real estate industry. Today he builds agentic intelligent systems, meaning AI agents that research, create content, nurture leads, and handle follow-up, to help mortgage and real estate business owners get found online, convert more leads, and scale. Gerry pairs decades of hands-on industry knowledge with the latest AI tools, so his clients stay a step ahead of the market.