
For most homeowners 62 and older who want to stop making monthly mortgage payments and stay in their home long-term, a HECM reverse mortgage is typically the stronger fit. If you have steady, documented income and can comfortably handle a new monthly payment, a cash-out refinance may deliver a larger lump sum at lower long-term cost. The 2026 HECM Maximum Claim Amount is $1,249,125, and every HECM requires HUD-approved counseling before you apply. Cash-out refinances require full income and debt-to-income (DTI) documentation, which rules out many retirees living on Social Security alone.
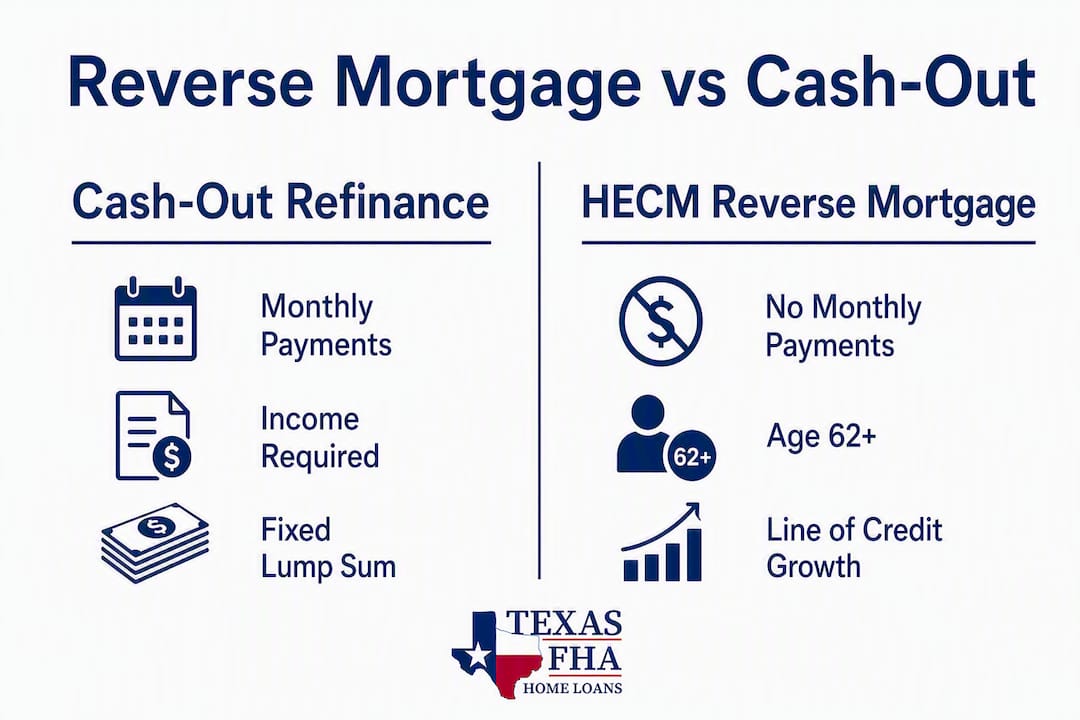
Rule of thumb: If you need to eliminate a mortgage payment and plan to age in place, consider a HECM. If you have steady income and want a large lump sum while continuing monthly payments, consider a cash-out refinance.
Your clearest next step: schedule a HUD-approved counseling session before pursuing a HECM, or request a refinance prequalification to test whether your income and DTI meet cash-out standards.
Key figure: The 2026 HECM Maximum Claim Amount is $1,249,125, set by HUD for Traditional HECM, HECM for Purchase, and HECM-to-HECM refinances.
Table of Contents
- How does a cash-out refinance work?
- How does a HECM reverse mortgage work, and what makes it different?
- Reverse mortgage vs cash-out refinance: side-by-side comparison
- What are the eligibility rules, and how much can you borrow?
- What do the costs and fees look like over time?
- How does repayment work, and what happens to your heirs?
- Which option fits your retirement goals?
- Worked example: how a HECM line of credit can grow
- Key Takeaways
- What retirees often get wrong about this decision
- TexasFHA helps seniors explore HECM and FHA refinance options
- Sources and further reading
How does a cash-out refinance work?
A cash-out refinance replaces your existing mortgage with a larger loan and pays you the difference in cash at closing. You walk away with a lump sum, and your new loan begins accruing interest and requiring monthly principal-and-interest (P&I) payments immediately.
The underwriting process is thorough. Lenders require:
- Full income documentation (W-2s, tax returns, pension statements, Social Security award letters)
- A credit score review
- A DTI ratio that typically must stay within lender-set limits
- A home appraisal to confirm current market value
- Standard closing costs: origination fees, appraisal, title, recording, and escrow charges
Cash-out refinances commonly allow borrowing up to a substantial portion of home value, subject to lender limits, often around 80%. For example, on a $400,000 home with no existing mortgage, you might access a significant lump sum before closing costs.
Common uses include paying off high-interest debt, funding a major renovation, or consolidating loans. One practical caution: resetting your loan term to 30 years when you are already 65 means you would be making payments into your mid-90s. Running the numbers on total lifetime interest paid, not just the monthly payment, is worth doing before you sign.
Net proceeds after closing costs are always less than the headline loan amount. Closing costs on a refinance typically run 2–5% of the loan balance, so factor that into your actual cash-in-hand calculation.
How does a HECM reverse mortgage work, and what makes it different?
A HECM (Home Equity Conversion Mortgage) is an FHA-insured reverse mortgage for homeowners 62 and older that lets the lender pay the homeowner, deferring all repayment until the borrower moves, sells, or passes away. No monthly mortgage payment is required as long as you live in the home as your primary residence and keep up property taxes, homeowner’s insurance, and basic maintenance.
Payout options and why the line of credit matters
HECMs offer five payout structures: a lump sum, a tenure payment (monthly payments for life), a term payment (monthly payments for a set period), a line of credit, or a combination of these. For retirement planning, the line of credit (LOC) option stands out. The unused portion of a HECM line of credit grows over time based on the current interest rate plus the annual mortgage insurance premium, which means your available borrowing power can increase as you age, even if home values stay flat.
What HECM eligibility actually requires
Primary HECM eligibility requirements are: the borrower must be at least 62, occupy the property as a primary residence, and complete HUD-approved reverse mortgage counseling before applying. Lenders perform a financial assessment to confirm you can continue paying property taxes and insurance, but there is no defined minimum credit score. Eligible properties include single-family homes, HUD-approved condominiums, and 2–4 unit properties where the borrower occupies one unit.
Pro Tip: Applying for a HECM line of credit earlier rather than waiting for a financial crisis can be a smart planning move. The LOC grows over time, so establishing it at 65 gives it years to expand before you need to draw on it.
One persistent misconception: a HECM is not a sale of your home. You retain the title. The loan becomes due only when you permanently leave the property. FHA mortgage insurance backs the loan, which means the non-recourse protection is real: you or your heirs will never owe more than the home’s appraised value at the time of sale, regardless of how large the loan balance has grown.
On the stigma: The perception that reverse mortgages are predatory has been substantially addressed by mandatory HUD counseling and FHA insurance protections that standardize borrower education and enforce non-recourse features across every HECM lender.
Reverse mortgage vs cash-out refinance: side-by-side comparison
| Dimension | Cash-Out Refinance | HECM Reverse Mortgage |
|---|---|---|
| Monthly payments | Yes — principal and interest begin at closing | No monthly P&I required (taxes/insurance still due) |
| Repayment timing | Ongoing monthly; loan paid off over term | Deferred until move, sale, or death |
| Eligibility | Income/DTI documentation, credit review, appraisal | Age 62+, primary residence, HUD counseling, financial assessment |
| How much you can borrow | Typically up to ~80% of home value (LTV) | Based on age, home value, and rates; capped at 2026 MCA of $1,249,125 |
| Major costs and fees | Origination, appraisal, title, closing (2–5% of loan) | Origination, upfront MIP (commonly 2% of home value), ongoing MIP, closing costs |
| Interest rate behavior | Fixed or adjustable; payments begin immediately | Fixed (lump sum) or adjustable (LOC/tenure); balance grows over time |
| Effect on heirs/equity | Equity preserved if payments made; heirs inherit net equity | Balance grows over time; heirs protected by non-recourse guarantee |
| Best use cases | Lump sum for homeowners with steady income and shorter time horizons | Eliminating payments, long-term cash flow, aging in place |
Practical takeaway: Financial experts frame these as serving different life stages — cash-out refinance for homeowners still working or with documented income, HECM for retirees prioritizing cash flow and staying in the home.
What are the eligibility rules, and how much can you borrow?
HECM eligibility checklist
To qualify for a HECM, you must meet every one of these requirements:
- Age 62 or older (all borrowers on title must meet this threshold)
- Primary residence (vacation homes and investment properties do not qualify)
- HUD-approved counseling completed before application
- Financial assessment showing ability to pay ongoing taxes, insurance, and maintenance
- Eligible property type (single-family, HUD-approved condo, or qualifying multi-unit)
The 2026 HECM Maximum Claim Amount is $1,249,125, which is the ceiling on the home value the FHA will use to calculate your principal limit. If your home is worth $1,500,000, the HECM calculation still uses $1,249,125 as the base. Your actual loan proceeds will be a fraction of that figure, determined by your age, current interest rates, and the MCA.
Cash-out refinance eligibility and borrowing limits.
Cash-out refinances are open to homeowners of any age, but the underwriting is strict. Lenders typically require documented income, a manageable DTI ratio, and a credit review. Many retirees on Social Security alone cannot meet the DTI and income documentation requirements for a cash-out refinance, making a HECM the only practical equity-access option in those situations.
| Metric | HECM | Cash-Out Refinance |
|---|---|---|
| Maximum home value used | $1,249,125 (2026 MCA) | No federal cap; lender-determined |
| Typical borrowing ceiling | Principal limit (age/rate/MCA formula) | ~80% of appraised home value |
| Upfront MIP | Commonly 2% of home value | Not applicable (unless LTV >80%) |
| Ongoing MIP | Yes (annual, added to balance) | Not applicable in most cases |
| Minimum credit score | None specified; financial assessment applies | — |
Use a HECM calculator to estimate your personal principal limit based on your age, home value, and current rates before meeting with a lender.
What do the costs and fees look like over time?
Both options carry real upfront costs, but their long-term cost profiles differ significantly.
Common closing costs for both options
- Origination fee (HECM: capped by FHA formula; cash-out: negotiated with lender)
- Home appraisal
- Title search and title insurance
- Recording fees and escrow/closing charges
- Third-party fees (attorney, survey, flood certification where required)
HECM-specific cost structure
HECM borrowers typically pay an FHA upfront mortgage insurance premium of commonly 2% of the home value, plus an ongoing annual MIP. Both the upfront MIP and origination fee can be financed into the loan, which reduces out-of-pocket costs at closing but increases the starting loan balance. From that point, interest and the ongoing MIP accrue on the growing balance each month.
On a $400,000 home, the upfront MIP alone would be approximately $8,000. Add origination fees and standard closing costs, and total upfront costs for a HECM can reach $15,000–$25,000 or more, depending on the home’s value and lender fees.
Cash-out refinance cost structure.
A cash-out refinance carries standard closing costs, typically a small percentage of the new loan balance, which can amount to several thousand dollars at closing. Unlike a HECM, the balance does not grow over time if you make your monthly payments. Extending the loan term, however, increases total lifetime interest paid, sometimes substantially.
Breakeven reality: Because HECMs include high upfront fees, they usually become cost-effective only if the homeowner plans to stay in the home for roughly a decade or longer. If you expect to move within five years, the upfront costs of a HECM are difficult to recoup.
Pro Tip: Ask any lender for a side-by-side multi-year cash-flow comparison using the same home value and time horizon for both options. Comparing only headline rates or monthly payments will not show you the full picture.
How does repayment work, and what happens to your heirs?
When each loan becomes due
A cash-out refinance requires monthly P&I payments from the first month after closing. Miss payments, and the loan can go into default. The loan is paid off when you sell, refinance again, or reach the end of the term.
A HECM has no monthly P&I obligation. The loan becomes due and payable when the last borrower permanently leaves the home, whether by moving to a care facility, selling, or passing away. The lender cannot call the loan early as long as you meet the ongoing obligations: property taxes, homeowner’s insurance, and basic upkeep.
Non-recourse protection and what it means for heirs
The HECM non-recourse guarantee is one of its most important features. Heirs are protected from owing more than the home’s sale proceeds: if the loan balance exceeds the home’s value at the time of settlement, FHA mortgage insurance covers the difference. Your heirs will never receive a bill for the shortfall.
When the borrower passes away, heirs typically have up to 12 months to settle the loan. They can:
- Sell the home and keep any proceeds above the loan balance
- Refinance the HECM into a conventional loan if they want to keep the property
- Deed the property to the lender if the loan balance exceeds the home’s value (no further liability)
How equity changes over time
With a cash-out refinance, making regular monthly payments preserves or grows your equity as the principal balance declines. With a HECM, the loan balance grows each month as interest and MIP accrue, which reduces the equity available to heirs over time. How much equity remains depends on how long the loan is outstanding, the interest rate, and whether home values appreciate.
Which option fits your retirement goals?
The single strongest deciding factor is whether you can qualify for and sustain monthly mortgage payments. If the answer is no, or if eliminating a payment is the primary goal, a HECM is almost always the more practical path.
Decision checklist
- How long do you plan to stay? HECM upfront costs favor a stay of 10 or more years. Cash-out refinance suits shorter horizons if you qualify.
- Can you qualify for monthly payments? Full income and DTI documentation is required for a cash-out refinance. If Social Security is your primary income, a HECM’s financial assessment is typically more accessible.
- Do you need a lump sum now or a safety line of credit? Cash-out delivers a lump sum. A HECM LOC grows over time and can serve as a long-term financial safety net.
- How important is leaving equity to heirs? Cash-out refinance with regular payments preserves equity. A HECM reduces it over time, though the non-recourse guarantee protects heirs from negative equity.
- Are you comfortable with a growing loan balance? HECM balances increase monthly. If watching the balance grow is a concern, a cash-out refinance with a declining balance may suit you better.
Questions to ask lenders and counselors
Before signing anything, ask for: a complete fee disclosure including all MIP and origination charges, a sample amortization schedule or LOC growth projection over 10–20 years, confirmation of HUD counseling documentation, the lender’s DTI thresholds for cash-out approval, and the servicing contact for ongoing questions after closing.
Red flags to watch for
Be cautious if a lender pressures you to decide quickly, claims you will retain full equity with a HECM, provides a vague or incomplete fee list, or makes inaccurate statements about how a HECM affects Medicaid eligibility or Social Security benefits. HECM proceeds are not taxable income and do not affect Social Security or Medicare, but they can affect Medicaid eligibility if funds are not spent in the month received. Consult a benefits counselor if Medicaid is a concern.
Pro Tip: Run a HECM estimate using the TexasFHA reverse mortgage calculator and get a cash-out prequalification from a lender before your HUD counseling session. Walking in with both sets of numbers makes the counseling conversation far more productive.
Worked example: how a HECM line of credit can grow
The HECM line of credit has a structural feature no HELOC or cash-out refinance can match: the unused portion grows over time. Here is a simplified illustration of what that can look like.
Assumptions:
- Borrower age: 68
- Home value: $500,000
- 2026 HECM MCA: $1,249,125 (home value is the binding cap here)
- Initial LOC amount (illustrative): $200,000
- Assumed effective rate (interest + MIP): 6.5% annually
- No draws taken in Years 1–5
| Year | Available LOC (no draws) | Notes |
|---|---|---|
| Year of origination | $200,000 | Initial principal limit allocated to LOC |
| Year 1 | — | Growth at ~6.5% on unused balance |
| Year 3 | — | Compounding continues |
| Year 5 | — | LOC has grown substantially without any draws |
| Year 10 | — | Nearly double the original amount. |
These figures are illustrative, based on HUD’s HECM LOC growth mechanism and assumed rates. Actual results depend on your specific interest rate, MIP, and lender terms.
By contrast, a cash-out refinance delivers a fixed lump sum at closing. If you took $200,000 at closing and made monthly payments, your available equity would not grow on its own — it would only recover as the balance paid down.
The LOC growth feature is most valuable for borrowers who establish the line early and draw on it selectively. Applying early can create a LOC that grows and serves as a proactive safety net, rather than a last resort accessed during a financial crisis.
Pro Tip: Use the FHA loan limit calculator to understand how the 2026 MCA interacts with your home value before estimating your principal limit.
Disclaimer: This worked example uses assumed rates and is for illustrative purposes only. It is not financial advice. Run your personal numbers with a HUD-approved counselor or a licensed lender before making any decision.
Key Takeaways
For most retirees, the choice between a reverse mortgage and a cash-out refinance comes down to one question: can you qualify for and sustain monthly payments, and do you want to?
| Point | Details |
|---|---|
| HECM suits payment-free retirement | Homeowners 62+ who want to eliminate monthly mortgage payments and age in place are the primary HECM candidates. |
| Cash-out requires income qualification. | Full DTI and income documentation is required; many fixed-income retirees cannot qualify for a meaningful cash-out amount. |
| HECM LOC grows over time | An unused HECM line of credit compounds at the loan rate plus MIP, increasing available funds without any action from the borrower. |
| Upfront HECM costs favor long stays. | The 2% upfront MIP and closing costs make a HECM most cost-effective for homeowners who plan to stay 10 or more years. |
| TexasFHA supports both paths. | TexasFHA offers HECM reverse mortgages and FHA refinancing with specialist guidance through HUD counseling and transparent fee estimates. |
What retirees often get wrong about this decision
Most people approach this comparison by looking at interest rates first. That is almost always the wrong starting point.
The rate on a HECM and the rate on a cash-out refinance are not directly comparable because the cash flows are structurally opposite. One requires you to pay every month; the other pays you, or at least stops requiring payment. Comparing them on rate alone is like comparing a salary to a pension by looking only at the tax bracket.
What actually matters first is the income test. If your documented income cannot support a new monthly payment, the cash-out refinance is not really an option regardless of how attractive the rate looks. Many retirees discover this only after spending time and money on an appraisal and application. A quick prequalification conversation with a lender, before any formal application, can save weeks of effort.
The second thing people underestimate is the value of the HECM line of credit as a planning tool rather than merely a crisis tool. Most borrowers apply when they are already under financial pressure. At that point, the LOC is smaller, the loan balance starts higher, and the growth period is shorter. Establishing the line at 65 or 68, even without drawing on it, can produce a meaningfully larger safety net by 75 or 80.
HUD counseling is not a formality. The counselors are independent, not paid by the lender, and they are required to walk through the full cost comparison with you. Treat that session as the most important hour in the process.
TexasFHA helps seniors explore HECM and FHA refinance options.
Seniors evaluating equity-release options deserve a lender who will show them the full picture before recommending anything. TexasFHA works with homeowners across Texas as a Full Eagle FHA-approved lender, offering HECM reverse mortgages and FHA refinancing with dedicated loan specialists who guide you through every step, including HUD counseling coordination and transparent fee estimates.
Before your first conversation with a TexasFHA specialist, it helps to have on hand: a recent mortgage statement (if applicable), a current property tax bill, proof of homeowner’s insurance, and a general sense of your monthly income sources. That is enough to start a meaningful conversation about which option fits your situation.
To review FHA loan requirements and qualification steps or to speak with a specialist about a HECM or FHA refinance, visit TexasFHA.org or call to schedule a no-pressure consultation. The goal is clarity, not a quick close.
Sources and further reading
The figures and eligibility rules in this article draw from primary HUD rulemaking documents, FHA mortgagee letters, and federal consumer protection resources. These are the authoritative sources for HECM rules, MCA limits, and borrower protections in the United States.
- HUD HECM program page — U.S. Department of Housing and Urban Development
- HUD Mortgagee Letter 2025-22 — 2026 HECM Maximum Claim Amount
- CFPB Reverse Mortgage Discussion Guide (PDF)
- TexasFHA: HECM reverse mortgage services and specialist support
- TexasFHA: unlocking home equity in retirement — FHA reverse mortgage guide
This article provides general information about mortgage options and is not financial, legal, or tax advice. Eligibility rules, rates, and costs change. Confirm current program details with a HUD-approved counselor or a licensed mortgage professional before making any decision.
Recommended
- Unlocking Home Equity In Retirement: An In-Depth Look At FHA Reverse Mortgages – Texas FHA Home Loans | First Time Buyer Loans
- Reverse Mortgage Calculator for Seniors: 2026 Guide
- HECM 101: What You Need To Know About Reverse Mortgage
- 2 Impactful Reasons To Refinance Your House – Texas FHA Home Loans | First Time Buyer Loans
Over 25 years of experience in the Mortgage business. A Digital Marketer specializing in Conversion Rate Optimization, Search Engine Optimization, and Artificial Intelligence Overview Optimization for the Mortgage and Real Estate industry.