

In recent years, there has been a noticeable increase in the adoption of alternative housing options in Texas, such as prefabricated homes and barndominiums. These architectural constructions offer advantages in cost-effectiveness and speed of construction. However, the financial aspects of these structures remain a topic of examination and often require careful understanding.
- Manufactured Homes
Conventional mortgage lenders have historically viewed manufactured homes as high-risk investments due to their high depreciation rates. However, newer financial products make it easier for prospective homebuyers to obtain loans for manufactured homes, often at competitive interest rates.
- Barndominiums
Frequently constructed on agricultural land, barndominiums function as living and working spaces. Due to their singular characteristics, conventional mortgages might not be readily applicable. Instead, construction loans followed by a conventional mortgage are becoming the norm.
- Down Payment
A substantial down payment, ranging from 10 to 20% of the total cost, is typically required for either type of housing. This barrier to entry for potential homeowners is being reduced through government-backed programs.
- Interest Rates and Terms
Manufactured homes and barndominiums can have variable interest rates, depending on credit score, loan term, and down payment amount.
- Government Programs
The Federal Housing Administration (FHA) is also entering the market, offering loans explicitly designed for this form of housing. These government-backed loans typically have lower required down payments and more favorable terms.
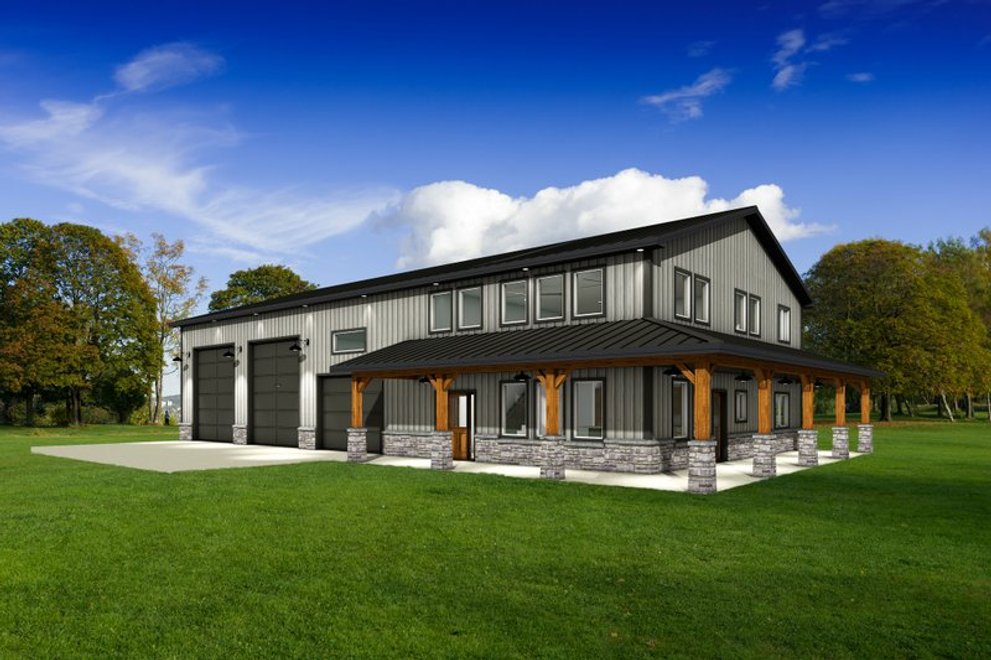
Barndominium Financing: Eligibility and Benefits
Financing a barndominium entails several methods, each with its requirements and benefits.
- USDA Loans
Appropriate for rural borrowers. Eligibility is contingent on meeting income and property requirements. Benefits include the possibility of lower interest rates and the option of no down payment.
- Traditional Mortgages
Regular home financing programs can finance barndominiums if the property meets the standards. There are credit score and down payment requirements.
- Low-Interest Construction and Purchase Loans
Certain lenders provide financing options specifically tailored for barndominiums. The credit requirements may exhibit a greater degree of flexibility.
- Specialized Barndo Financing
Some financiers only offer barndominiums. A minimum 620 credit score and a minimum down payment of 3% may be required.
Is a Barndominium For You?
Maintaining a clean credit record, practicing responsible money management, and setting aside more money for a down payment will increase your eligibility for various lending programs.
In the current economy, barndominiums present a vital substitute for conventional dwellings. These can be built quickly and at a lower cost, giving designers and space managers more creative freedom. Additionally, barndominiums are frequently more energy-efficient and require less upkeep. Because of these features that cut costs, they are becoming a more and more popular housing option that satisfies the expectations of the present market for sustainability and affordability.

Over 25 years of experience in the Mortgage business. A Digital Marketer specializing in Conversion Rate Optimization, Search Engine Optimization, and Artificial Intelligence Overview Optimization for the Mortgage and Real Estate industry.