FHA Streamline Refinance in Texas
An FHA streamline refinance in Texas lets a homeowner who already has an FHA-insured mortgage replace it with a new FHA-insured mortgage, usually with less paperwork than a standard refinance and no new appraisal.
What Is an FHA Streamline Refinance?
HUD’s Single Family Housing Policy Handbook 4000.1 defines a Streamline Refinance as the refinance of an existing FHA-insured mortgage “requiring limited Borrower credit documentation and underwriting.” The new loan proceeds must pay off the existing FHA-insured first mortgage. HUD underwrites every streamline manually under its manual-underwriting rules; automated approvals don’t count for this program.
“Streamline” refers to the reduced documentation, not to fewer rules. HUD still sets requirements for seasoning, payment history, borrower benefit, loan amount, and term. The FHA-approved mortgage company that funds the loan can add its own requirements too.
If you don’t have an FHA loan today, or you want to take equity out, a streamline isn’t the right tool. Our FHA refinance loans page compares the other FHA refinance options.
Quick Facts
- Only for existing FHA loans. A streamline pays off an FHA-insured first mortgage with a new FHA-insured mortgage.
- No appraisal. HUD doesn’t require one, and the home’s current value doesn’t change the loan amount.
- Two versions. Non-credit-qualifying (no credit report or income review required by FHA) and credit-qualifying (a full manual review of credit and capacity).
- It must help you. HUD requires a “net tangible benefit,” such as a lower combined rate, a move from an adjustable rate to a fixed rate, or a shorter term.
- Timing and history matter. You need at least six payments on the loan, 210 days since it closed, and a recent on-time payment history.
- Not a cash-out loan. Cash back at closing is limited to $500.
Who Qualifies for an FHA Streamline Refinance in Texas
HUD’s rules apply the same way anywhere in Texas. On the date the FHA case number is assigned, the handbook requires that:
- You’ve made at least six payments on the FHA loan being refinanced. If you modified the loan, the six payments must be under the modification; if you assumed it, they must be since the assumption.
- At least six full months have passed since the loan’s first payment due date.
- At least 210 days have passed since the loan closed.
- Your recent payment record is clean. For the non-credit-qualifying version, all mortgage payments on the home must have been made within the month due for the six months before case number assignment, with no more than one 30-day late payment in that period, and the payment for the month before closing must also be made within the month due.
Forbearance. If you had mortgage forbearance, HUD treats your payment history as acceptable for the non-credit-qualifying version once the forbearance plan is complete and you’ve made at least three consecutive monthly payments on time since. If you’re still in forbearance or haven’t made those three payments yet, you may qualify for the credit-qualifying version if your payments were on time for the six months before forbearance.
Occupancy. Streamlines can be used for a principal residence, a HUD-approved secondary residence, or a non-owner-occupied property. Second homes and rentals can only refinance into a fixed-rate loan. To qualify the home as your principal residence, the mortgage company must see proof such as employment records, utility bills, or electronic address verification; otherwise, it will process the loan as non-owner-occupied, which affects the maximum loan amount. Our post on FHA occupancy requirements explains the basics.
Non-Credit-Qualifying vs. Credit-Qualifying
Non-credit-qualifying streamline
FHA doesn’t require a credit report for this version, and many of the standard underwriting sections, including minimum credit score, income, asset, and debt-to-income ratio reviews, don’t apply. You may use a shortened loan application, but you must still answer the occupancy question. The catch: every borrower on the current loan must stay on the new loan. HUD allows one exception. A borrower can be removed after divorce, legal separation, or death if the divorce decree or separation agreement awarded the home and payment responsibility to the remaining borrower (where applicable) and the remaining borrower shows they’ve made the payments for at least six months before case number assignment. People can be added without a credit review.
Credit-qualifying streamline
Here, the mortgage company pulls credit and reviews income, assets, and debts under HUD’s manual underwriting rules, but still doesn’t need an appraisal. At least one borrower from the current loan must remain on the new one. Our pages on FHA loan requirements and debt-to-income ratios explain what that review covers.
Individual mortgage companies may still check credit or set score minimums on a non-credit-qualifying file. We’ll tell you up front what the company reviewing your file expects.
The Net Tangible Benefit Test
HUD won’t insure a streamline that only adds cost. The handbook defines a net tangible benefit as a reduced “combined rate” (the interest rate plus the annual mortgage insurance premium rate), a change from an adjustable-rate to a fixed-rate mortgage, and/or a reduced term that results in a financial benefit to the borrower.
The exact test depends on what you have now and what you’re moving to. For example, when a fixed-rate FHA loan is refinanced into another fixed-rate loan without shortening the term by three years or more, the new combined rate must be at least 0.5 percentage point below the old one. Moves from an adjustable rate and term reductions of three years or more have their own tests in HUD’s chart. Passing HUD’s test doesn’t by itself make a refinance right for you.
Closing Costs, Cash Back and Mortgage Insurance
- Loan amount. For an owner-occupied home or HUD-approved second home, the new base loan amount can’t exceed the lesser of the current principal balance (plus interest due, late charges, escrow shortages and mortgage insurance due) or the original principal balance including any financed upfront premium, minus any upfront premium refund. For investment properties, you can’t add those extra items.
- Closing costs. Because the formula above doesn’t include closing costs, you usually pay them at closing or cover them with a credit. If your funds to close exceed the new loan’s total monthly payment, the mortgage company must verify the source of the money. New subordinate financing is allowed only to pay down the FHA loan or to cover closing costs, prepaid items or discount points.
- Cash back. Estimates can’t result in more than $500 cash back at closing. A refund of your old escrow balance doesn’t count toward that limit.
- Term. The new loan’s term can be no longer than the remaining term on your current loan plus 12 years, or 30 years, whichever is less.
- Upfront premium refund. If you refinance an FHA loan into another FHA loan within three years, part of the upfront mortgage insurance premium (UFMIP) you paid is credited toward the new loan’s upfront premium. HUD’s schedule starts at 80% in the first month and drops to 10% by month 36.
- Annual premium. HUD’s Appendix 1.0 sets the annual premium, and for a streamline FHA uses the home’s original value to figure the loan-to-value ratio.
The CFPB explains how to compare offers on your Loan Estimate and check final figures on your Closing Disclosure, and its guide to mortgage insurance covers FHA premiums. Our closing costs page lists typical items in Texas.
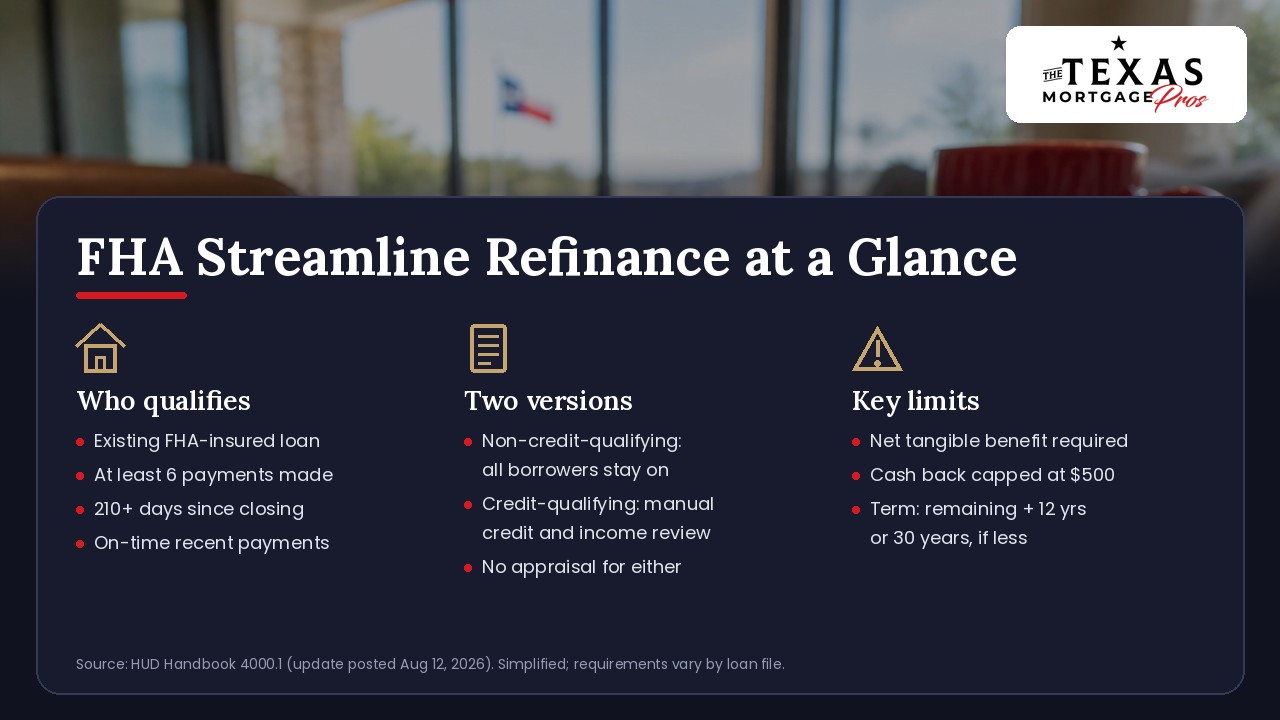
No appraisal required by HUD
At least six payments made on the loan
At least 210 days since the loan closed
A net tangible benefit is required
Cash back at closing limited to $500
Term no longer than remaining term plus 12 years, or 30 years
How an FHA Streamline Refinance Works, Step by Step
- Quick review. Share your latest mortgage statement. We confirm the loan is FHA-insured and check seasoning dates and recent payments.
- Pick the version. Based on who’s on the loan, your occupancy and your goals, we identify whether a non-credit-qualifying or credit-qualifying streamline fits.
- Benefit check. We compare your current loan with the proposed structure under HUD’s net tangible benefit test and walk through the estimated costs.
- Application and case number. You complete the application and initial disclosures. The FHA case number date is the date HUD’s seasoning and payment-history tests are measured from.
- Underwriting. The mortgage company reviews the payoff statement, payment history, occupancy evidence and, for credit-qualifying files, credit, income and assets. There’s no appraisal.
- Title and closing. A Texas title company handles title work and the closing. Review your Closing Disclosure carefully, and keep making your current payment on time, since the payment for the month before closing must be made by the due date.
Timelines vary with document, title, and payoff turnaround, and none is guaranteed. Ready to start? Use our FHA refinance application.
Documents to Gather
- Your most recent mortgage statement (the mortgage company will order the official payoff statement).
- Photo ID for each borrower.
- Homeowners insurance declarations page.
- Proof you live in the home, such as a utility bill or employment records.
- If your mortgage isn’t on your credit report or isn’t in your name: a verification of mortgage or 12 months of bank statements showing on-time payments.
- If you had a modification or forbearance plan in the past 12 months: the plan and proof of the payments made under it (COVID-19 forbearance doesn’t need plan documentation).
- Divorce decree, separation agreement or death certificate if a borrower is coming off the loan.
- For credit-qualifying files: recent pay stubs, W-2s or tax returns and bank statements.
Send documents only through the secure upload link you’re given, never by regular email.
Do and Avoid
Do
- Make every mortgage payment within the month it’s due, right up to closing.
- Find your original closing date and first payment date so we can check seasoning.
- Ask how the new loan meets HUD’s net tangible benefit test.
Avoid
- Assuming “streamline” means no rules or no closing costs.
- Expecting cash out; the limit is $500.
- Removing a co-borrower without checking which version that requires.
- Waiting until the upfront premium refund window has passed, if timing is otherwise right.
Want a deeper dive on whether a streamline makes sense? Read our blog post on the FHA streamline refinance, and if you’re refinancing from a conventional loan instead, see how to refinance a conventional loan to FHA in Texas.
FHA Streamline Refinance FAQ
Do I need an appraisal for an FHA streamline refinance?
No. HUD’s handbook says appraisals aren’t required on streamline refinances, and having one doesn’t change your eligibility or maximum loan amount.
Will my credit be checked?
FHA doesn’t require a credit report for a non-credit-qualifying streamline, but a credit-qualifying streamline requires one. Some mortgage companies also check credit on non-credit-qualifying files.
Can I take a co-borrower off the loan?
On a non-credit-qualifying streamline, only after divorce, legal separation or death, and the remaining borrower must show six months of payments. Otherwise, a credit-qualifying streamline may work if at least one original borrower stays on.
Can I get cash out?
No. Cash back is limited to $500, not counting a refund of your old escrow balance. For equity access, ask about other FHA refinance options.
Talk With a Texas FHA Streamline Broker
Have an FHA loan and wondering whether a streamline fits? Call (281) 801-6965 to talk with a mortgage professional at The Texas Mortgage Pros, or contact us online. We’ll review your current loan, explain which version applies and outline the documents you’ll need.
This page is general information, not legal, tax or financial advice, and is not a commitment to lend or an offer of credit. Loan approval and terms are subject to underwriting, program guidelines and the requirements of the FHA-approved mortgage company. Meeting HUD’s streamline requirements does not guarantee approval or a lower payment. FHA rules can change; HUD’s revised refinance section of Handbook 4000.1 carries a November 10, 2026 effective date. Last verified: October 27, 2026.
The Texas Mortgage Pros, LLC | Company NMLS #2665861 | Gerry Nicodemus, NMLS #286371 | Equal Housing Opportunity | www.nmlsconsumeraccess.org | (281) 801-6965
Trustindex verifies that the original source of the review is Google. Gerry and Reggie walk you through the entire process slowly. They will answer your call at anytime of day. Very knowledgeable and polite. Understood we would have MANY questions and answered them all. I highly suggest them if you want buying a house to be very minimal stress.Trustindex verifies that the original source of the review is Google. I had such a good experience using Gerry and his team several years ago with an FHA loan purchase that when I was in the market to purchase a second property recently, I immediately contacted Gerry without even considering other lenders. Gerry and his team are true professionals when it comes to navigating the various obstacles and pitfalls that can arise during the home buying process which resulted in another successful real estate transaction for me. I would definitely use Gerry's services again in the future and would encourage others to do the same.Trustindex verifies that the original source of the review is Google. Gerry and his team are true professionals and experts in their field. They knew exactly what to do with our set of circumstances, and made our lending experience run like clockwork. I loved that Gerry was available to answer questions whenever we needed him, and he gave us clear and honest answers to everything. We couldn't have asked for a better experience.Trustindex verifies that the original source of the review is Google. My wife and I were looking for the best Texas FHA home loan company, and after qualifying several different companies, we decided to use Gerry. Throughout the process, from start to finish, Gerry and his team walked us through purchasing our first home. We initiated our loan process while RVing in WA state, and was able to easily communicate with each other. All in all, the process took about two months (including the time it took for us to pick our favorite house over a selection of ~60). Gerry, our main point of contact with this FHA loan company in Texas, was always full of energy, excitement, and positive emotions while talking to us. And if we ever had any questions, he would spend as much time as needed to enlighten us. After my experience with this company, I have become more aware of the process of buying a house, getting a loan, and what to expect. And because of the knowledge that we've gained in addition to the aforementioned benefits, we give this loan company 5 stars.Trustindex verifies that the original source of the review is Google. Gerry was our lender on the purchase of our forever home. Gerry is very professional and knowledgeable, he walked us thru every step explaining the do's and dont's, always giving his honest and helpful opinions. If we didn't understand something he would explain it to us no questions asked. Gerry is a Godsend and we could never thank him enough, we thanked God every day for Gerry. Will definitely be recommending Gerry to anyone looking to purchase a home, they can't go wrong having him as their lender.Trustindex verifies that the original source of the review is Google. I highly recommend Gerry and his team! After speaking to several other lenders, we were left feeling confused and ill prepared. Gerry helped us get on track with everything we would need in order to qualify. This was our first time purchasing a home and he was there every step of the way to explain and answer all of our questions in a way that we fully understood. Gerry is very knowledgeable, professional, prompt, and personable! Next week, we close on our dream home!!!Trustindex verifies that the original source of the review is Google. I got the opportunity to work with Gerry Nicodemus. He did an amazing job. He was incredibly helpful. He guided me through the whole process and was available every time I had a question. I definitely would recommend Gerry and rest of the Texas FHA staff.Trustindex verifies that the original source of the review is Google. Gerry was very helpful in the process. Being new to Texas, I really didn’t know what to expect. However, Gerry and his crew answered every question and made the home buying process seem so easy.Trustindex verifies that the original source of the review is Google. I started this process so nervous, but Gerry explained every step of the way and put my mind at ease. This has been a great experience, thanks to Gerry!